BUYING A RESALE PROPERTY
Resale purchase payment calculator.
Explore the purchase contribution, stamp duties and loan repayments for a private residential resale home in Singapore.
Add optional purchase costs and compare available cash and assumed eligible CPF funds. The result is a planning illustration; funding eligibility and payment timing need confirmation.
Your purchase illustration
Illustrative housing loan
Calculated or entered loan; not a borrowing approval.Total non-loan funds
Price contribution, BSD, ABSD and entered cost allowances.Monthly loan repayment
Constant-rate illustration over the entered tenure.Where the funds go
- Purchase price outside the loan
- Buyer’s Stamp Duty
- Additional Buyer’s Stamp Duty
- Entered other cost allowances
- Total non-loan funds
- Price above lender valuation (included in price contribution)
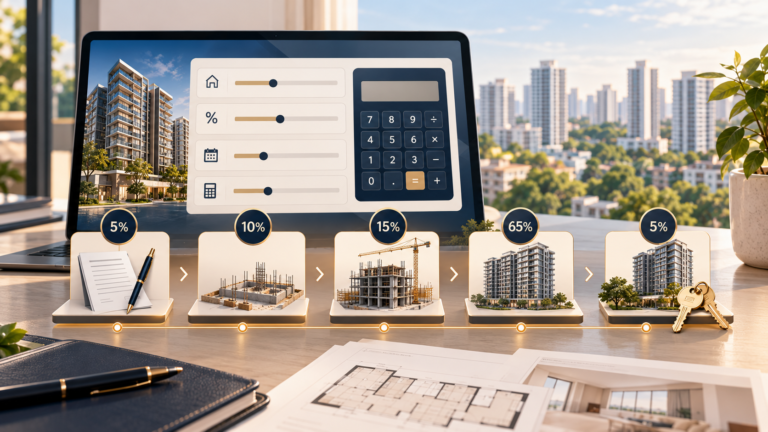
Illustrative purchase-payment sequence
Option fee · assumed 1%
Part of purchase price, not an additional cost.Exercise payment · assumed 4%
Brings the illustrative deposits to 5%.Remaining non-loan price funds
After those deposits; excludes duties and other costs.Deposits are included once in the price contribution. This sequence assumes a standard 1% / 4% private resale arrangement; it does not predict due dates. Your agreement and conveyancer determine the actual amounts, cash requirements and release timing.
Funding comparison under your assumptions
- CPF assumed allocated to remaining price funds
- Entered CPF not allocated in this illustration
- Cash needed under this allocation
- Cash shortfall under this allocation
- Cash remaining under this allocation
This allocation reserves the illustrative 5% deposits for cash, caps CPF at the remaining non-loan price contribution, and assumes duties and all other cost allowances are paid in cash. It can overstate cash needs if approved CPF use covers some duties or legal fees. It can understate compulsory cash needs where your financing or valuation requires more cash. Zero shortfall is not confirmation that your cash/CPF split or timing is sufficient.
Scope: private residential resale purchases with standard individual-buyer BSD and ABSD rates, reviewed 12 October 2026. Joint buyers, companies, trusts, treaty treatment and reliefs require separate assessment. No ABSD refund is assumed. CPF eligibility and lender approval are not assessed. Inputs are processed in your browser and are not submitted or stored by this tool. References: IRAS BSD, IRAS ABSD, MoneySense financing and CPF housing guidance.
Plan the funds and the timing.
Option and exercise payments form part of the purchase price. They are included once, not added again to the total non-loan funds. The displayed sequence assumes 1% and 4% deposits; your contract may differ.
Compare your planned loan with your lender’s actual assessment. The number of outstanding housing loans determines the financing scenario; the number of residential properties held affects ABSD. They are separate questions.
Available CPF does not replace every cash requirement. Confirm the eligible amounts, minimum cash contribution and release arrangements with your lender and conveyancer, including any price above valuation.
For a focused estimate, use our residential property stamp duty calculator for BSD and standard individual ABSD.
Planning your purchase beyond the numbers? Read our step-by-step guide to buying a property in Singapore to understand the process and what to prepare before committing.
Discuss My Purchase Plans