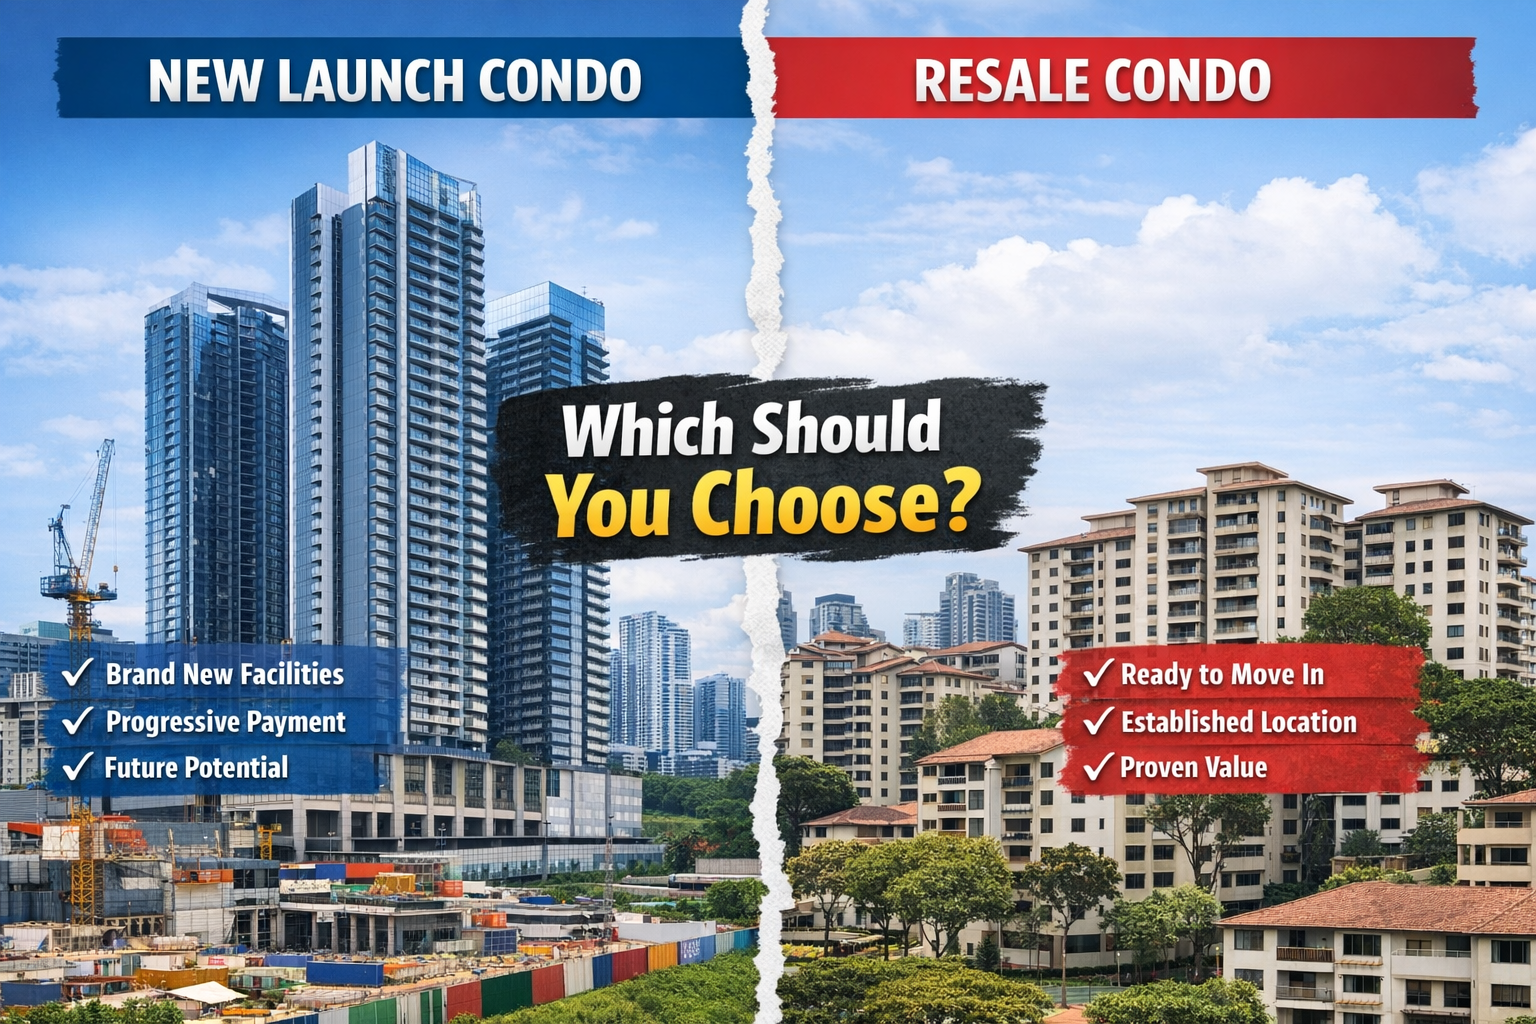
Choosing between a new launch and a resale condo in Singapore starts with your budget, move-in date and the home you need.
A new launch may offer a preferred unit and new facilities, while a resale property lets you inspect the actual home and its surroundings.
Either can be a suitable purchase at the right price.
For this comparison, “new launch” means an uncompleted private condominium bought from a developer. Completed developer stock can have a different payment and possession timeline. Executive Condominiums have separate eligibility and ownership rules.
- When do you need a home you can occupy?
- What is your full budget, including the cost of waiting or renovating?
- Which specific unit best fits your household and a realistic holding period?
New launch vs resale condo: the practical differences
- Move-in timing
- New launch: wait for construction and possession. Resale: agree completion and possession with the seller, allowing for any tenancy and renovation.
- What you can inspect
- New launch: plans, specifications, models and show units. Resale: the actual apartment, common areas and neighbourhood.
- Payment timing
- New launch: payments typically follow contractual construction milestones. Resale: the purchase balance is generally settled at completion.
- Condition and upkeep
- New launch: new finishes with contractual defects procedures. Resale: condition varies, and repairs or renovation may be needed.
- Evidence for pricing
- Compare both against relevant completed transactions, adjusting for tenure, age, layout, size and location.
1. Match the purchase to your move-in deadline
If you need to relocate for school, caregiving or work, a home that will only be ready years later may not solve the immediate problem. Budget for where you will live during the wait, including rental renewals and moving costs.
For an uncompleted purchase, distinguish an estimated TOP date from the contractual vacant possession date in the sale and purchase agreement. Allow time for key collection, inspection, rectification and furnishing. Review the documents with your conveyancer rather than planning around a brochure date alone.
A resale condo can offer an earlier move, but check whether it is sold with a tenancy or vacant possession, whether the seller needs an agreed extension, and how long renovation will take. “Completed” does not necessarily mean “available immediately”.
2. Compare the total commitment, not just price per square foot
Price per square foot helps with comparison, but it does not tell you whether a home works for your family. A smaller unit can have a lower total price and still leave you short of usable space.
A larger home can be affordable to buy but expensive to renovate and maintain.
For each shortlisted unit, add the purchase price, stamp duties, legal fees, financing costs, renovation or furnishing, moving expenses and any accommodation needed before occupation. Keep an emergency reserve outside that budget.
A simple cost-of-waiting example
Suppose an uncompleted home requires you to rent elsewhere for 30 months at $3,500 a month. That is $105,000 in accommodation costs, before moving expenses or any rent increase. If a resale alternative needs $70,000 of renovation, compare both within their complete purchase budgets.
These hypothetical amounts do not establish which property is cheaper. The properties may differ in size, location and condition, and you may already have somewhere to live. The purpose is to put the waiting period into your comparison.
3. Understand progressive payments and the eventual mortgage
An uncompleted developer purchase typically uses a contractual stage-payment schedule. The loan is drawn progressively as required, so early repayments may be lower while less of the loan is outstanding. The exact contribution sequence and repayments depend on your financing arrangements.
Lower early repayments do not reduce the purchase price or guarantee a cheaper loan overall. Check the instalment when the full loan is drawn, the applicable interest rates and your ability to manage overlapping housing costs.
Payments follow construction milestones rather than a guaranteed monthly timetable.
Use our new launch progressive payment calculator to explore payment stages and loan assumptions. Treat its LTV setting as an illustration, then confirm the actual approved loan with your lender.
Bank financing is subject to assessment, TDSR and LTV limits. The TDSR threshold is 55%; the applicable LTV depends on outstanding housing loans, age and tenure. A 75% loan is not available to every buyer. See MoneySense’s affordability guidance.
4. Inspect the space you will actually use
For a new launch, study the floor plan and specifications alongside the show unit. Check room dimensions, storage, air-conditioning ledges, balcony space, ceiling details and which fittings are included. Identify show-unit upgrades so you can budget for the home as delivered.
For a resale property, visit at different times if practical. Check noise, afternoon sun, ventilation, lift access, parking and the route to public transport.
Look for signs of leaks and ask about alterations and approved plans. A viewing cannot reveal every defect; consider an independent inspection where appropriate.
Compare where beds, desks, dining furniture and storage will go. Avoid assuming all newer layouts are efficient or all older apartments are spacious. The specific floor plan matters more than the label.
5. Check maintenance and project condition
New developments can still have defects and ongoing maintenance costs. Review the contractual defects liability period and reporting procedure, and inspect promptly after taking possession. URA’s home-buying guidance explains checks for uncompleted purchases and existing properties.
For resale condos, review available management information on maintenance charges, the sinking fund, planned major works and any special levies. Ask your conveyancer what records can be obtained.
An older project with careful upkeep may be more suitable than a newer one with unresolved maintenance issues.
For leasehold property, check the actual remaining lease. A newly completed building does not necessarily start with a fresh 99-year lease on key collection. Tenure can also affect financing, CPF use and future buyer demand.
6. Apply the same tax and exit checks to both
Both purchases can attract Buyer’s Stamp Duty and, depending on your profile and ownership, Additional Buyer’s Stamp Duty. BSD is calculated on the higher of purchase price or market value. Check IRAS’s BSD guidance and our ABSD planning guide.
If you own an HDB flat or EC, confirm the applicable occupation and ownership conditions before committing to a private-property purchase. Buying before selling also requires a plan for tax, loan eligibility and when sale proceeds become available.
Do not assume either option will deliver a profitable exit. Entry price, competing supply, upkeep, remaining lease and future demand all matter. Our property exit strategy guide covers the holding-period and sale-proceeds checks to make before planning a later move.
Which option fits your situation?
A new launch may suit you when:
- You have stable accommodation for the construction period and flexibility if plans change.
- The specific unit, location and specifications meet your needs.
- You can fund the early contributions and eventual full mortgage comfortably.
- You have assessed the price against alternatives without relying on future appreciation.
A resale condo may suit you when:
- You need an earlier move and can agree a workable possession date.
- You want to assess the actual apartment and established surroundings.
- You have budgeted for its condition, renovation and project maintenance.
- The layout and total cost compare well with your other options.
Shortlist actual units from both categories using the same budget and household requirements. Reject options that fail an essential need before ranking the remaining ones by price, condition and convenience.
Compare homes with your plans in mind
Francis and Hui Ming can help compare shortlisted new launch and resale units, review transaction evidence and map the purchase timeline around your household.
Reviewed 18 October 2026. General information only. Confirm financing, eligibility, tax and contractual terms before committing to a purchase.